
Digital payments are growing, but SMEs still need funding to scale

AI summary
Digital payments are giving South Africa’s small businesses a clearer record of their trading activity, but having a transaction history does not necessarily mean they can access the capital needed to take on larger contracts.
The distinction is becoming increasingly important as more businesses move towards electronic payments and mobile financial services. While these records can help lenders understand how a business operates, they may not show whether it has the resources to fulfil a significant new order.
The issue is expected to feature in discussions at the Africa Tech Festival in Cape Town, where mobile money and financial technology are among the topics shaping conversations about business growth across the continent.
Figures from the GSMA’s 2026 report show that global mobile-money merchant payments reached $155 billion in 2025, a 42% increase from the previous year. East Africa accounted for nearly three-quarters of that growth.
Research by the World Bank also indicates that businesses accepting electronic payments are around three percentage points less likely to be fully credit-constrained, with the benefits particularly relevant to smaller and younger enterprises without audited financial statements.
However, digital payment records are only one part of the information lenders need when assessing a funding application.
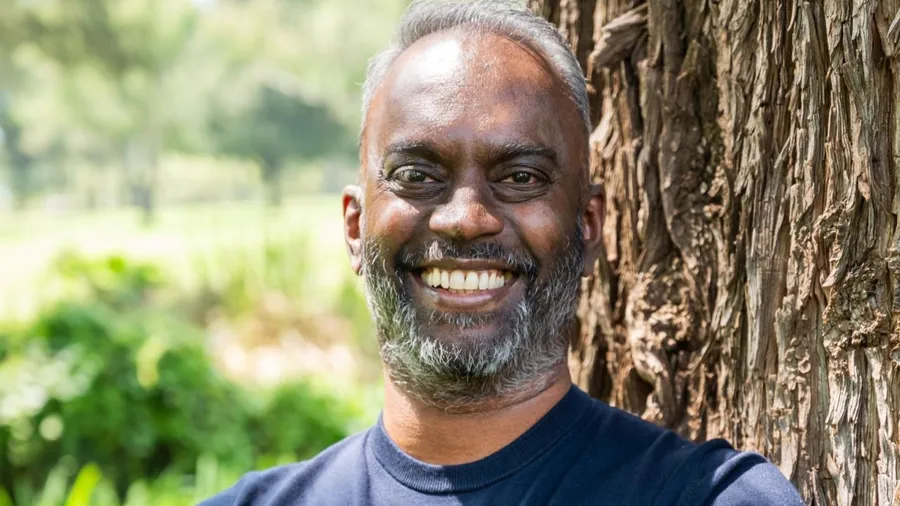
Andrew Maren, founder and CEO of fintech company ProfitShare Partners, says digital transactions can help establish that a business has customers and generates income, but they do not necessarily demonstrate whether it can manage the financial demands of a larger commercial opportunity.
‘A digital payment history demonstrates that a business has active customers, which is a vital starting point,’ says Maren.
He points to the example of a distributor that regularly records modest sales before securing a substantial purchase order from a corporate client.
While its transaction history may confirm that the business is operating, Maren argues that it does not establish whether the company can fulfil the order profitably or whether the buyer has the financial standing to meet its payment obligations.
The challenge, therefore, extends beyond identifying businesses with consistent sales. Lenders also need to assess the commercial details of the work a company has secured, including the buyer, contract terms and costs involved in delivery.
The wider financing environment remains a concern for South African small and medium-sized enterprises (SMEs).
The OECD’s Financing SMEs and Entrepreneurs 2026 report identifies limited credit information, gaps in business records and a lack of finance-ready enterprises among the barriers affecting access to funding. It estimates that only between 8% and 20% of micro, small and medium-sized enterprises receive finance through formal financial service providers in their capacity as businesses.
More recently, a Visa report on South African SMEs, published in November 2026, highlighted another gap in the digital transition: while electronic payments are widely used, many businesses still manage financial administration and daily operations across separate systems. Only 41% of surveyed SMEs were using an integrated platform connecting payments with broader business management.
These findings point to the importance of looking beyond the payment itself. Better financial records can help businesses demonstrate their trading activity, but access to suitable funding also depends on how lenders evaluate their broader operations and individual business opportunities.
ProfitShare Partners says it aims to address this challenge through short-term funding linked to verified purchase orders, contracts and invoices.
Rather than relying exclusively on a business’s historical financial performance, the company assesses the specific transaction for which funding is requested. This includes examining the credibility of the buyer and the financial viability of the deal.
The approach is intended to help qualifying SMEs secure the capital required to fulfil larger orders without necessarily having to provide traditional collateral or demonstrate an extensive financial track record.
For businesses that have won work but lack the upfront cash to purchase stock, pay suppliers or cover delivery costs, this type of funding can address a different need from conventional lending.
Maren believes closer cooperation between digital payment providers and financing institutions could help lenders build a more complete understanding of small businesses and the opportunities available to them.
As digital financial services expand, the next challenge will be ensuring that the information generated by everyday transactions can be used responsibly to support more informed lending decisions.
Maren also highlights the importance of safeguards around data sharing, particularly as financial institutions and technology providers explore ways to use business transaction records when assessing creditworthiness.
‘Getting paid digitally proves an SME has traction,’ he says. ‘The real test for the financial sector now is ensuring these businesses receive the capital required to deliver the work they have secured, allowing them to build an even stronger trading history.’
For South African SMEs, the distinction is significant: accepting digital payments can help establish a record of business activity, but turning that activity into sustainable growth may depend on whether funding is available when a new commercial opportunity arises.
Be the first to know – Join our WhatsApp Channel for content worth tapping into! Click here to join!
Also read:
Picture: Supplied
The post Digital payments are growing, but SMEs still need funding to scale appeared first on Cape Town ETC.
Follow the story
About this article
- Length
- 854 words · 4 min read
- Published
- November 15, 2026
- Byline
- Lulama Klassen
- Source
- Cape Town ETC