

Navigating digital economy: China’s lessons for Malawi
By Chimwemwe Mangazi in Beijing, China: We arrived at Beijing Capital International Airport around six in the evening; tired, hungry and still trying to understand the size of the city. I was in the company of four other journalists from Benin, Cameroon, Chad and Rwanda. From the airport, we had another hour on the road to Renmin University of China, where we were to take part in the China International Press Communication Centre programme for the next three-and-a-half months. By the time we got

AI summary
By Chimwemwe Mangazi in Beijing, China:
We arrived at Beijing Capital International Airport around six in the evening; tired, hungry and still trying to understand the size of the city.
I was in the company of four other journalists from Benin, Cameroon, Chad and Rwanda.
From the airport, we had another hour on the road to Renmin University of China, where we were to take part in the China International Press Communication Centre programme for the next three-and-a-half months.
By the time we got to the university, another half hour went by as we registered at our dormitory. The body wanted rest, but the stomach had its own demands.
After settling in, our colleague, Rousa Shikoha from Namibia, who had arrived earlier, asked if anyone wanted to go out for a snack at one of the canteens or restaurants on campus.
I was not going to sleep on an empty stomach. So, I went down to meet the others.
We walked around campus looking for food, but only one restaurant was open. Since it was our first night, we agreed to start with something familiar before testing Chinese dishes. That decision took us outside the campus.
A few hundred metres north of Renmin University, we saw a McDonald’s outlet. It looked like rescue.
We entered without hesitation. As we usually do in Malawi, I went straight to the counter to place an order. But the worker, speaking in Chinese, pointed to a digital board behind me.
None of us understood what she was saying.
Seeing our confusion, she left the counter and walked us to the digital ordering machine. The screen had a long list of meals. She helped us choose what we wanted and pressed the button for payment.
That is when the real lesson began.
We had just arrived in China and did not yet have local bank accounts. Luckily, Shikoha had some yuan notes. She reached into her purse and pulled out cash.
However, the worker waved her hand. The message was clear; payment was supposed to be through digital means.
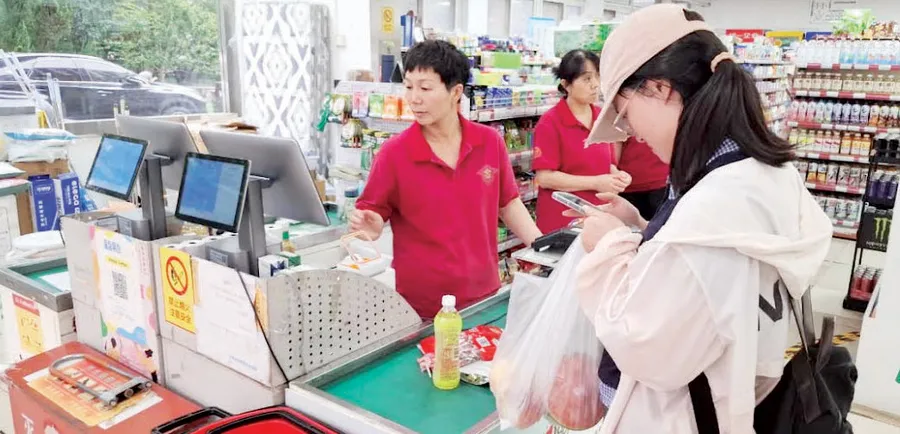
SELF SERVICE—A customer completes a purchase using digital payment spots in a grocery shop
Behind us, other customers were waiting. We were holding up the line. Then, a young man, likely a student from Renmin University or a nearby institution, stepped forward. He offered to pay for our food using his phone while we gave him the cash.
That night, what we needed most was supper. But what we got, apart from burgers and fries, was a clear picture of how deeply digital payments have become part of life in China.
For the next few days, before our bank accounts were set up, we survived through the kindness of students and strangers.
In shops and restaurants, we would approach someone, offer cash and ask them to pay for us through their phones.
It felt strange at first. But to the Chinese, it was normal.
China runs largely on two major payment platforms, WeChat Pay and Alipay. WeChat is a social media and messaging platform, almost like WhatsApp, but it is also connected to one’s bank account and phone number.
Alipay is mainly a digital payments platform used for shopping, money transfers, e-commerce and other services.
One of the assistants in the programme, Qiang Baoyi, said China’s digital payment system works because it is linked to a formal banking structure and real identity.
She said having a phone number alone is not enough for a person to fully use WeChat Pay or Alipay.
“Chinese citizens can open a personal bank account independently from the age of 16. Children under 16 may open accounts with the guardian’s documents and consent.
“For local Chinese users, to fully use digital payment, you need real-name authentication, usually by binding a Chinese bank account. A local phone number is mainly for receiving verification codes,” Qiang said.
Qiang also said ordinary consumers are not punished for choosing digital payment systems.
“For ordinary daily consumption payments such as shopping, restaurants and transport, there is no transaction fee deducted from consumers. There is also no separate government tax collected on every single payment transaction. Taxes are handled by merchants according to China’s tax rules, not charged directly to consumers per payment,” he said.
This is one of the biggest lessons for Malawi.
In China, people use digital payments because they are easy, fast and affordable. The system does not make people feel that they are losing money each time they choose to pay digitally.
Another programme assistant, Xiong Run, said the amount displayed is the amount deducted, which builds trust among users.
“Consumers do not pay transaction fees. The price you see is what gets deducted. The fee is paid by the merchant, typically around 0.3 percent.
“Your phone can be offline because the payment QR code can be generated offline. The merchant’s device must be online to complete the deduction,” Xiong said.
This means digital payments have been made simple even for small purchases. A customer buying water, bread or a bus ticket does not need to calculate extra charges.
Back home, Malawi is still pushing for a digital economy, but the numbers show that the journey is facing pressure.
The latest National Payments System Report by the Reserve Bank of Malawi (RBM) shows that digital payments activity slowed in the first quarter of 2026. The country’s payment system processed 631.8 million transactions worth K52 trillion between January and March 2026.
This was a 9.2 percent decline in transaction volumes and a 28.4 percent drop in value from the previous quarter, when 696.1 million transactions worth K72.7 trillion were processed.
RBM attributed the reduced activity to the “traditionally subdued transactional patterns of the first quarter of the year” and structural inefficiencies within the payment ecosystem.
However, the Consumers Association of Malawi (Cama) sees another problem; the cost of using digital platforms.
The government introduced a 0.05 percent levy on electronic bank transfers and mobile money transactions above K100,000 effective December 31, 2025. This came alongside an increase in Value Added Tax rate from 16.5 percent to 17.5 percent.
Cama Executive Director John Kapito said consumers are feeling the pressure.
“Consumers are really feeling the bite on these digital money transactions. As such, consumers are now finding ways of transacting outside the digital transactions system.
“I think, maybe by the end of this year, we’ll see a big shift, where people are moving away from these digital financial systems. People will continue to avoid using such transactions. I think people are now keeping their money at home,” Kapito said.
The China experience shows that a digital economy grows when people are encouraged, not punished, for using digital platforms. Malawi can learn that low cost transactions create trust, habit and volume.
Removing levies on electronic payments, reducing transaction fees and allowing consumers to pay exactly what they see would make digital platforms attractive again.
The government can still collect taxes through businesses, incomes and formal systems without charging people on every single transaction.
If Malawi wants a strong digital economy, the phone must become a bridge, not a burden.
Follow the story
About this article
- Length
- 1,183 words · 6 min read
- Published
- September 22, 2026
- Byline
- Chimwemwe Mangazi
- Source
- The Times Group